AU Small Finance Bank credit cards
Every AU Small Finance Bank card we list, with its fees and what it's good for. Compare them side by side, and talk to an advisor before you apply.
- Cards listed
- 6
- With no yearly fee
- 1
- With lounge access
- 3
Popular AU Small Finance Bank cards
AU Small Finance Bank
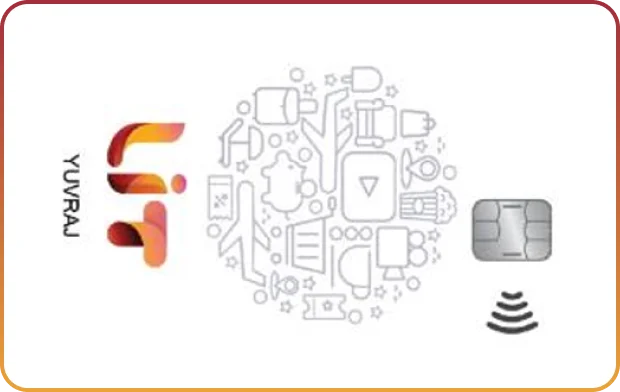
AU Lit
Best for: Cashback on everyday spends
- Joining fee
- Nil
- Annual fee
- Nil
- Up to 5% cashback @ ₹299.
- 10X/5X on domestic/international spends.
- Up to 2% cashback @ ₹199.
AU Small Finance Bank
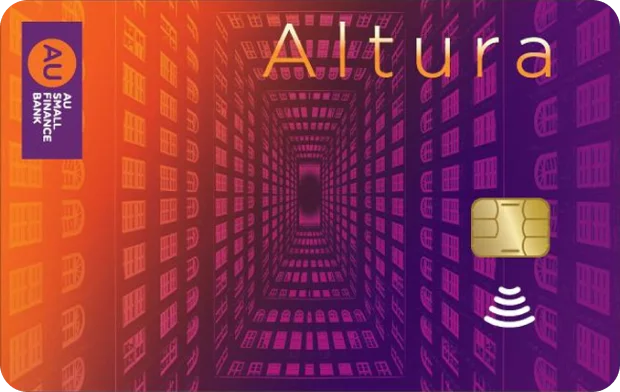
AU Altura
Best for: Cashback on everyday spends
- Joining fee
- ₹199
- Annual fee
- ₹199
- Up to 2% Cashback on bills & other retail spends.
- Up to 5% Cashback on spends.
- Up to 2 complimentary at railway stations.
AU Small Finance Bank
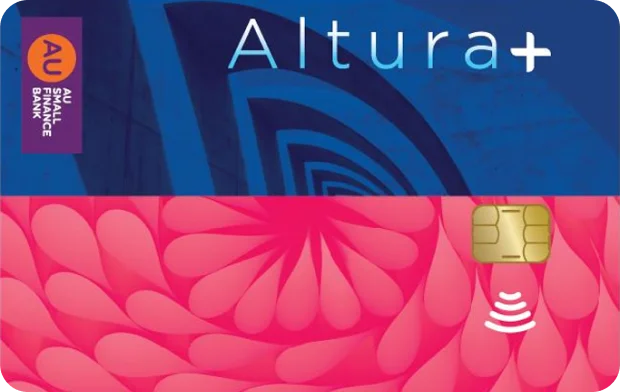
AU Altura Plus
Best for: Shopping, online and in store
- Joining fee
- ₹499
- Annual fee
- ₹499
- Vouchers worth ₹500 on ₹10,000 spend.
- Up to 2 reward points per ₹100 spent on online.
- Up to 2 complimentary lounge access per calendar quarter at railway stations.
AU Small Finance Bank
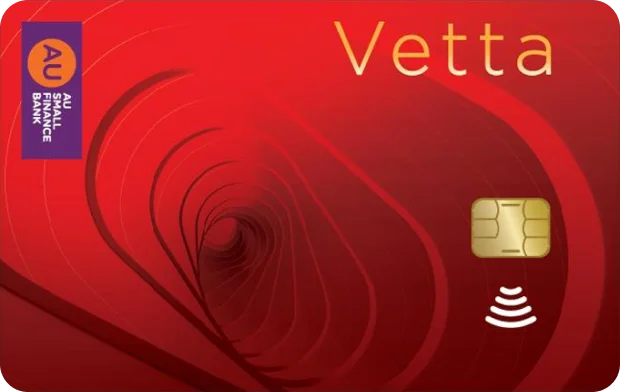
AU Vetta
Best for: Earning reward points
- Joining fee
- ₹2,999
- Annual fee
- ₹2,999
- Up to 10 Reward Points per ₹100 on spends.
- Up to 1,000 bonus reward points on your birthday.
- Vouchers worth ₹2,000 on a minimum of ₹30,000 spends.
AU Small Finance Bank
AU Zenith+
Best for: Travel and airport lounges
- Joining fee
- ₹4,999
- Annual fee
- ₹4,999
- Up to 16 complimentary movies tickets.
- Up to 16 domestic/international lounge access.
- Buy 1 Get 1 Free movie ticket on BookMyShow.
AU Small Finance Bank
AU Zenith
Best for: Eating out and ordering in
- Joining fee
- ₹7,999
- Annual fee
- ₹7,999
- Vouchers worth ₹1,000 on spends of ₹2 lakh.
- Up to 2 domestic/international lounge access.
- Up to 2 lounge access at railway stations.
Card fees and benefits last verified 20 Sep 2026. Banks change them without notice, and a card's own terms are the final word. We'll confirm the current terms with you before you apply.
AU Small Finance Bank credit card fees and charges
Fees differ by card. These are the charges that apply across most cards, and the figures each card's own terms will confirm.
Joining and annual fee
Charged once when the card is issued and again each year. Many cards waive the annual fee once your yearly spends cross a threshold.
Interest on unpaid balances
Charged per month on anything you don't pay by the due date, and on cash withdrawals from the day you take them. It is quoted monthly — multiply by twelve to see the yearly cost.
Late payment fee
A slab-based fee that rises with the amount outstanding, plus GST. Paying even the minimum by the due date avoids it.
Foreign currency markup
A percentage added to spends in another currency, including on foreign websites. Travel cards charge the least.
Cash withdrawal fee
A percentage of the amount withdrawn, with a minimum. Interest also runs from day one, so treat a card as the last place to take cash from.
What AU Small Finance Bank cards offer
The benefits that come up most often across the AU Small Finance Bank cards we list. Each card's own page of terms is the final word.
- Up to 2 complimentary lounge access per calendar quarter at railway stations
- Up to 16 domestic/international lounge access
- Up to 2 domestic/international lounge access
How to choose a credit card
Start from your own bank statement, not from the card with the longest benefits list.
- 01
Match the rewards to your biggest spend
Look at where your money actually went last month. A fuel card is worth little if you take the metro, and a travel card earns nothing if you fly once a year.
- 02
Weigh the fee against what you'll really earn
A ₹5,000 fee card that returns 5% on ₹20,000 of monthly spends is worth it. The same card on ₹5,000 of spends is not.
- 03
Check the fee-waiver threshold
Many cards waive the annual fee once you spend a set amount in a year. Check whether that number is one you'd hit anyway, without spending more to reach it.
- 04
Read the caps and exclusions
Reward rates usually have monthly caps, and categories like rent, fuel, wallet loads, insurance and government payments often earn nothing.
Applying through MultiBankers
Check Offers- Step 1
Tell us how you spend
Your income, your biggest spend categories and whether you want a fee-free card. Two minutes, one form.
- Step 2
We shortlist and check
An advisor matches you to cards you're likely to be approved for, and tells you which ones you aren't — before an application touches your credit report.
- Step 3
Apply once, with help
We help you with the documents and stay with you until the card is in your hand.
We are here to answer
all your questions
Start with the category your money goes to. Compare the cards on this page by joining fee, annual fee and what each one is best at, then check whether the annual fee is waived at a spend level you'd reach anyway. If you're unsure, tell us your monthly spends and an advisor will narrow it to two.
It depends on the card: entry-level cards ask for less than premium ones, and the bank also looks at your credit score, your existing loans and how much of your current limits you use. AU Small Finance Bank sets and revises these limits itself, so we don't publish a figure we haven't confirmed. An advisor can tell you which cards your income fits before you apply.
Most banks decide within a few working days once the documents are complete, and the card is dispatched after that. An incomplete application is the usual reason for a delay, which is why we check the paperwork with you before it goes in.
Tell us which card you're interested in and an advisor will call you, confirm what you're likely to be approved for and take you through the application. We are not AU Small Finance Bank, and the bank makes the final decision on every application.
No. We don't lend money. Loans are sanctioned and disbursed by our partner banks and NBFCs, which make the final decision.
Thinking about a AU Small Finance Bank card?
An advisor will tell you which one fits, and which you're likely to be approved for, before you apply.